Best MYGA Companies: 9 Companies Compared
We compared the best myga companies on guaranteed terms, insurer strength and withdrawal rules so you can weigh a fixed annuity with clear eyes before you buy.

- Editor's choice
 Athene
Strong rates with top strength ratings
Starts atSee websiteVisit athene.comFull review - Great alternative
 Canvas Annuity
Online buying and competitive rates
Starts atSee websiteVisit canvasannuity.comFull review - Also consider
 Gainbridge
Direct online purchase
Starts atSee websiteVisit gainbridge.ioFull review
TL;DR:
- A MYGA, or multi-year guaranteed annuity, locks in a fixed interest rate for a set term, usually two to ten years, much like a bank CD issued by an insurer.
- Rates vary by term, deposit size and state, and the highest advertised rate often requires a large deposit, so compare the rate you would actually receive.
- Insurer financial strength matters more than a small rate edge, since MYGA guarantees rest on the insurer and your state guaranty association, not the FDIC.
- Watch for surrender charges and market value adjustments, which can reduce what you get if you withdraw early.
- Shorter terms suit money you may need sooner, while longer terms usually pay more but tie your money up for years.
Quick comparison
| Tool | Best for | Starts at | Free plan? | |
|---|---|---|---|---|
| Athene | Strong rates with top strength ratings | See website | No | Visit |
| Canvas Annuity | Online buying and competitive rates | See website | No | Visit |
| Gainbridge | Direct online purchase | See website | No | Visit |
 MassMutual | Financial strength and brand stability | See website | No | Visit |
 Nationwide | Large insurer with broad terms | See website | No | Visit |
 Pacific Life | Established insurer, multiple terms | See website | No | Visit |
 Symetra | Competitive multi-year terms | See website | No | Visit |
 Protective Life | Straightforward guaranteed terms | See website | No | Visit |
 Aspida | Higher-rate multi-year options | See website | No | Visit |
The best MYGA companies
We focused on insurers with a current MYGA product, a meaningful market presence and published terms you can actually compare. Rates change often, so we describe each company's approach and where its strengths lie rather than treating any single rate as permanent. This is general information, not financial advice, and annuities carry surrender charges, tax rules and state-specific limits worth reading before you buy.
Athene is one of the first names most MYGA shoppers meet, and for good reason. Its MaxRate product has appeared near the top of October 2026 rate listings, with five-year rates around 6 percent for larger deposits in many states, and the company carries an A+ rating from AM Best. That combination of rate and strength is hard to beat, and it is why Athene suits buyers who want a strong rate without dropping far down the ratings scale.
The details still matter. Rates differ by state and by deposit band, and smaller deposits often earn less than the headline figure. Athene contracts also carry surrender periods and, on some versions, a market value adjustment, so this is money to set aside for the full term. If you can commit the funds and meet the deposit band, Athene is a strong default quote.
- Competitive rates on longer terms
- A+ financial strength rating
- Well known MYGA lineup
- Best rates often need larger deposits
- Early withdrawals can face surrender charges
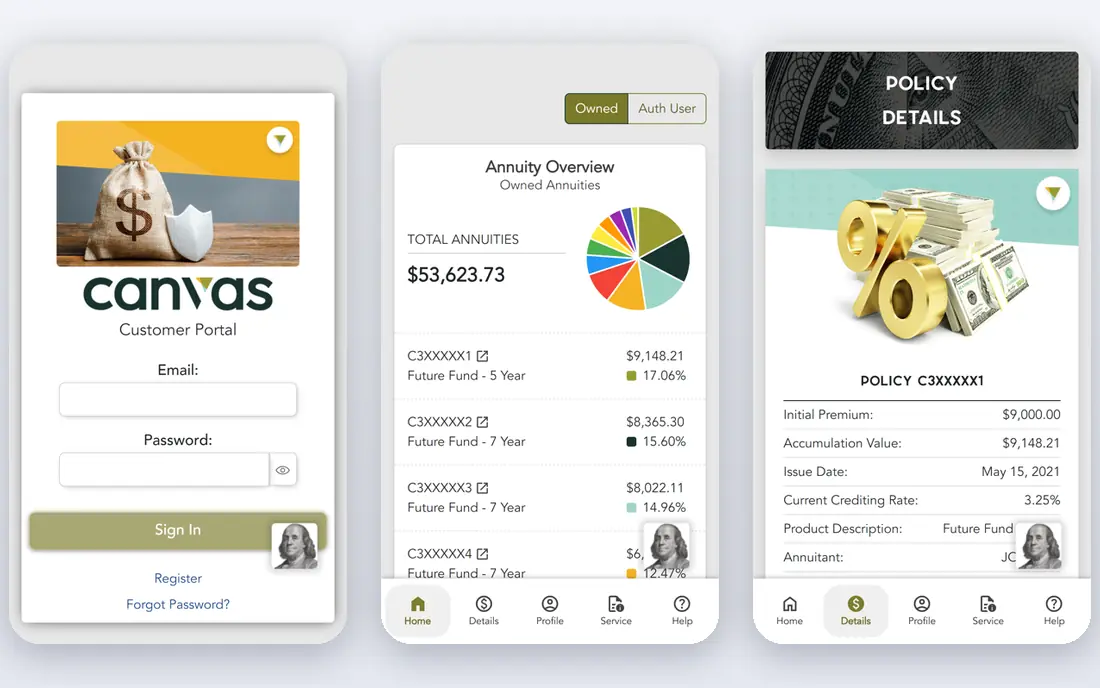
Canvas, issued by Puritan Life, has built its reputation on a direct, online-first MYGA with rates that often sit near the top of three, five and seven-year listings. October 2026 listings showed its Future Fund product at competitive levels across several terms. For buyers comfortable applying online without an agent, the process is refreshingly simple compared with traditional annuity sales.
The trade-off is insurer strength. Canvas carries a B++ rating from AM Best, which is good but below the A ratings of the largest carriers. That does not make it a bad choice, but it does mean you should understand your state guaranty association limits and keep the deposit within a range you are comfortable with. Rate-focused buyers who accept that balance will like Canvas.
- Direct online application
- Competitive rates across terms
- Simple product lineup
- Lower AM Best rating than the biggest mutuals
- Fewer agent support options
Gainbridge sells annuities directly online, which appeals to buyers who want to compare and purchase without a sales appointment. Its SteadyPace MYGA appears regularly in rate listings for four and five-year terms, and the site lays out terms in plain language. If you already know you want a MYGA and roughly which term fits, Gainbridge makes the mechanics easy.
What you give up is hand-holding. Complex questions about taxes, beneficiary designations or rolling over qualified money may need outside advice. Gainbridge also prices by state and term, so the rate you see online may differ from a friend's in another state. For confident, self-directed buyers, it is a convenient option.
- Fully online buying experience
- Clear product pages
- Competitive mid-length terms
- Rates vary by term and state
- Limited agent guidance for complex cases
MassMutual is the choice for buyers who rank safety above squeezing out the last fraction of a percent. As a mutual insurer with top strength ratings, it offers a level of balance-sheet comfort that smaller, higher-rate carriers cannot match. Its Stable Voyage MYGA has appeared in recent rate listings with a solid five-year rate for larger deposits, which keeps it competitive even if it rarely tops the charts.
Expect a more traditional buying path, usually through an agent, and a rate that may sit below Canvas or Athene on the same term. For retirement money where stability matters most, that trade is reasonable. MassMutual also services a wide annuity range, which can simplify things if you already hold policies there.
- Top-tier financial strength
- Long mutual company history
- Broad annuity range
- Rates can trail the highest online sellers
- Agent channel for most purchases
Nationwide's Secure Growth MYGA has shown up in October 2026 five-year rate listings near 6 percent for larger deposits, paired with an A+ AM Best rating. That puts it in the same conversation as Athene for buyers who want both rate and strength. Nationwide also offers a wide range of annuity and insurance products, which can be handy if you prefer one carrier relationship.
As with other large carriers, the headline rate usually assumes a larger deposit, and state variations apply. Surrender charges and withdrawal rules need a careful read, particularly the free withdrawal allowance. Nationwide suits buyers who want a household-name insurer without giving up much rate.
- A+ financial strength rating
- Broad product lineup
- Well known brand
- Top rates often require larger deposits
- Terms vary by state
Pacific Life offers MYGA products such as Pacific Harbor and Expedition II, which have appeared in recent rate listings at competitive levels for multi-year terms. The company carries an A+ AM Best rating and a long history in the annuity market, which gives cautious buyers comfort. Multiple term lengths let you match the contract to when you expect to need the money.
The product lineup can be confusing, since similar-sounding versions carry different rates and withdrawal terms. Work through the illustration with an agent or adviser and confirm the exact rate, term, surrender schedule and market value adjustment for your state. Pacific Life rewards careful comparison rather than a quick click.
- A+ financial strength rating
- Several MYGA term options
- Long operating history
- Rates vary by product version
- Agent channel for most sales
Symetra's Select Max and Select Pro MYGA products have appeared in recent rate listings with competitive three and five-year rates, particularly at higher deposit levels. The company holds an A rating from AM Best, placing it in solid company for buyers who want a blend of rate and strength. Its product structure is relatively straightforward, which helps when comparing terms side by side.
State availability and deposit bands are the usual caveats. A rate that looks strong nationally may be lower in your state or at your deposit size, so get a quote for your exact situation. Symetra is a good middle-ground pick for buyers who want a strong rate from a well rated carrier.
- Competitive rates on several terms
- A rating from AM Best
- Clear product structure
- Best rates often need larger deposits
- Availability varies by state
Protective Life's SecureSaver MYGA has appeared in recent five-year rate listings near 6 percent for larger deposits, with an A+ AM Best rating behind it. The appeal here is simplicity: a guaranteed rate for a set term from a strong insurer, without exotic features. That makes Protective a good fit for buyers who want a MYGA to do one job well.
Rate chasers may find higher figures elsewhere, especially from direct online sellers. Protective also distributes through multiple channels, so confirm you are comparing the same product version and rate. For a set-and-forget fixed annuity from a strong carrier, Protective is a steady choice.
- A+ financial strength rating
- Simple guaranteed-rate structure
- Broad distribution
- Rates can trail the highest online carriers
- Product versions differ by channel
Aspida's Synergy Choice MYGA has featured prominently in October 2026 rate listings, with five-year rates near the top of the market for larger deposits and competitive seven-year terms too. The company carries an A- rating from AM Best, which is a respectable strength level for a rate-leading carrier. Buyers who want a longer term and a strong rate will find Aspida hard to ignore.
Aspida is less of a household name than MassMutual or Nationwide, and its best rates again sit in higher deposit bands. Read the surrender schedule and any market value adjustment carefully, and confirm state availability. If the rate and term fit your plan, Aspida offers a compelling mix of yield and reasonable strength.
- Competitive rates on five and seven-year terms
- A- financial strength rating
- Several term choices
- Best rates need larger deposits
- Less widely known than the biggest mutuals
How we picked these
We reviewed October 2026 MYGA rate listings, carrier financial strength ratings and product pages, focusing on insurers with a current, purchasable MYGA and a clear term lineup. We compared rates across terms, deposit bands and ratings, and we favored carriers that appear consistently in rate data rather than one-day outliers. We did not purchase annuities or receive personal illustrations, so our notes reflect published listings and carrier documentation. Rates change frequently and vary by state, so any figure here should be rechecked at quote time.
How to choose a MYGA term and carrier
Start with timing, not rate. Pick a term that ends when you are likely to want the money, whether that is three years for near-term flexibility or seven years for a longer horizon. A higher rate on a term that outruns your plans can cost more in surrender charges than it earns. Next, weigh rate against strength. A small rate gap between an A+ carrier and a B++ carrier may be worth accepting if the stronger balance sheet helps you sleep better, and state guaranty limits should factor into how much you place with any one insurer.
Then read the withdrawal rules. Most MYGAs allow a free annual withdrawal, often around 10 percent, but amounts above that can trigger surrender charges and possibly a market value adjustment. Ask for the full surrender schedule in writing, confirm whether the rate is simple or compound interest, and check how taxes apply to your qualified or nonqualified money. A short call with a licensed adviser can be worthwhile for larger deposits, since annuity tax and surrender rules are unforgiving once the contract is signed.
FAQ
What is a MYGA?
A multi-year guaranteed annuity is a fixed annuity that pays one guaranteed interest rate for a set term, usually two to ten years. It works a bit like a bank CD, but it is issued by a life insurer, grows tax-deferred and is not FDIC insured. Your guarantee rests on the insurer and your state guaranty association.
Are MYGA rates fixed for the whole term?
Yes, the headline rate is guaranteed for the initial term you choose. After the term ends, you can usually withdraw the money, renew at the then-current rate or roll it into another annuity. Check whether renewal rates are guaranteed or set at the time of renewal.
What happens if I withdraw early from a MYGA?
Early withdrawals above the free allowance usually face surrender charges, and some contracts add a market value adjustment that can raise or lower the payout. Withdrawals of gains before age 59 and a half can also carry a 10 percent IRS penalty on top of ordinary income tax. Read the surrender schedule before buying.
How safe is a MYGA?
Safety depends on the insurer's claims-paying ability, since MYGAs are not FDIC insured. Higher AM Best ratings signal stronger financials, and state guaranty associations provide a backstop up to state limits. Spreading large sums across carriers and staying within guaranty limits are common precautions.
How much money do I need to buy a MYGA?
Minimums vary by carrier and product, often starting around 5,000 to 10,000 dollars, with the best rates sometimes requiring 100,000 dollars or more. Confirm the minimum and the deposit band for the rate you are quoted, since both affect your return.